I wanted to throw up. My body flashed hot and cold, and I could feel the blood thumping in my temples like giant drums. My thoughts raced like wild fire, a tempest out of control.
I kept thinking about what I could do with the $1,000 I had just lost in the stock market. I could have paid down more of my student loans. I could be that much closer to eliminating the PMI on my mortgage. I could just have it in my bank account as an emergency fund.
It would take me weeks of work to regain that money after taxes and normal cost of living. What was I thinking putting my money in something risky like stocks? Stupid, stupid, stupid!
Asset Allocation is a fundamental part of investing. Which investments should we own? What percentage of total investments should we allocate to equities, bonds, Real Estate, or alternatives? As an American, should I purchase International assets, or focus solely on US assets?
There is an incredible amount of research on this topic, considering factors from expected duration of retirement to personal temperament. Perhaps you’ve heard some of the sound bite versions of this research, such as “Hold a percentage of stocks equal to 100 minus your Age.” So if, for example, you were 40 years old, you would hold 60% stock and 40% bonds
Like most mainstream investment advice, it is targeted at people that plan to retire at 65 and live until they are 80. Which is why as an early retiree, this advice (and most mainstream advice) is harmful at best
Tossing conventional wisdom to the side, over the past several years I’ve been moving our asset allocation towards 100% equities. Let’s explore why
It just happened. Not in the way good things happen when you aren’t expecting it, more in the way of how you might describe a horrible accident
“This guy was crossing the street, and a big truck just came out of nowhere, and BOOM… it happened”
Back in 2006 the real estate market in the Seattle area was hot. Prices were on the rise, and the press was full of stories of people making tons of cash rehabbing properties. People were even quitting their day jobs to flip houses.
I had taken advantage of the hot market to sell my own house, choosing instead to live in a small apartment in a walkable neighborhood. I wasn’t interested in real estate myself, but I was interested in building some passive income streams
House flippers were in need of short term cash. As it so happened, I had some. So I started lending money to a few people with incredible return rates. They would get the cash they needed to remodel a house for 2-6 months, I would get a percentage of the profit from the sale of the home. Yield was sometimes 10-20% per month!
This was great! What could possibly go wrong? A lot, apparently
I was on the wrong track. Work was consuming all of my waking hours, and my house was a time and money sink hole. I was angry and frustrated. I wanted out
I looked at my most recent bank statement. Last month I had earned $0.06 in interest. 6 cents?! I was doomed!
I had a mortgage and a student loan. Most of my savings was locked up in my 401k or home equity, and the value of the latter was highly questionable
I needed some passive income. Who wants to continue trading hours for dollars, when money can magically appear in your bank account while you sleep? The late night infomercials promised over night success
Of course like most good magicians, behind the illusion is years of hard work, dedication, and practice. It is one thing to understand how to earn income while you lounge on the beach, and another to make it happen
But if you are diligent and overcome the challenges, one can go from being burdened by debt to having assets that earn more than your cost of living in a relatively short period of time.
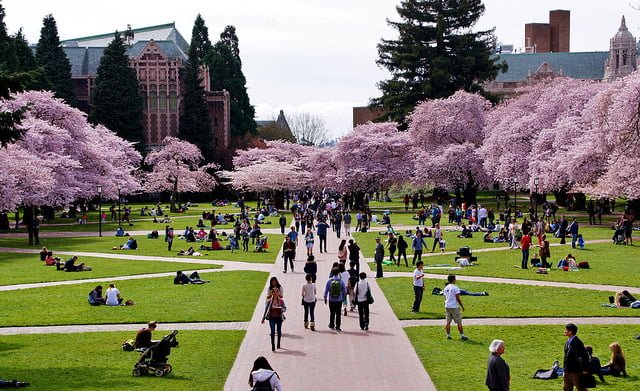
The University of Washington (Winnie’s Alma Mater)
With a child on the way, we have lots to think about. What to name him/her, how to get all the proper nutrients, natural birth vs. C-section, and how to pay for college
It might be a little early to be thinking about college, but that is the point of biggest concern shared in comments on the blog and on reddit about our estimate for the cost of raising a child. In general, people are concerned that I am too optimistic about stock returns and not pessimistic enough about the rate of growth in tuition